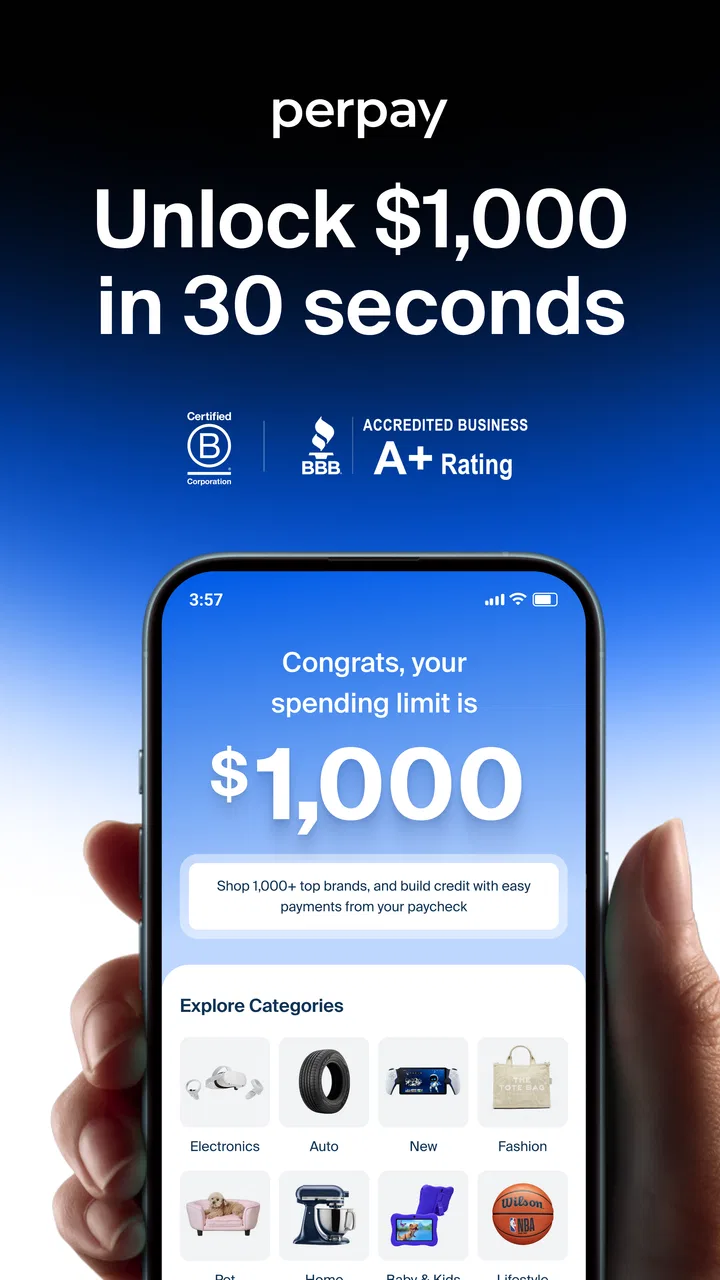
Perpay - Shop and Build Credit
- 4.8
- Rating
- 1.00M
- Installs
- Free
- Price
 Analysis by App-foxy
I approached Perpay - Shop and Build Credit as a finance app first and a shopping app second. That distinction matters. Its central idea is to connect everyday purchases with a path toward building credit, rather than treating shopping and credit activity as completely separate tasks. In my experience, that makes it more interesting than a basic budgeting app, but it also means you need to understand the terms and your own repayment habits before using it seriously.
The app is free, aimed at everyone, and comes from Perpay Inc. It has become a substantial service in its category, with over a million installs and a 4.8 average from around 11 thousand ratings. Those figures suggest that many people find the basic experience useful, but they are not a substitute for checking whether its approach fits your financial situation. A finance app can feel convenient and still be the wrong choice if it encourages purchases you would not otherwise make.
How the current Perpay experience fits into everyday finances
I find it useful to judge Perpay by how it would fit around the money routines a household already has, rather than treating it as a shared shopping account. In a home where people coordinate purchases, the key question is who makes the decision and who is responsible for each payment. That practical boundary matters even more when several people use the same device.
You May Also Like

 Blood Strike: 2.5 Anniversary
Blood Strike’s Loadouts Turn Every Drop Into a Tactical Gamble
A close look at Blood Strike’s custom loadouts: how fast access to signature weapons reshapes its battle royale rhythm, rewards preparation, and narrows the gap between fights.

 Pandora - Music & Podcasts
Pandora’s Music Is Easy to Start, but Harder to Recover
Pandora’s strength is its low-effort path from a seed to a station. Its weak spot is how much confidence it asks you to place in connection, setup, and quiet recovery.

 8 Ball Pool
 Is Built on Rivalries, Rematches, and Routine
A close look at the rivalries, rematches, shared routines, and unanswered safety questions that turn a quick pool match into a persistent mobile community.

 Samsung Music
’s Quiet Strength Is Playing What You Already Own
Its reach comes less from spectacle than from dependable access to a personal library. That simplicity is both the app’s strongest retention engine and its ceiling.

 AccuWeather: Weather Radar
AccuWeather Review: A Quick, Clear Forecast for Everyday Decisions
For everyday plans, the best forecast is the one you can understand quickly. AccuWeather makes rain timing, radar, and local conditions easy to act on, with a few trade-offs.

 Hill Climb Racing
Why Hill Climb Racing Still Turns Crashes Into One More Run
A tiny car, a bumpy hill and one more upgrade: Hill Climb Racing keeps resurfacing because its simple chaos makes every near-miss feel personal.
More From Our News Desk



A shopping route with a credit-building purpose
The most useful way to think about Perpay is as a guided purchasing system. Instead of opening a traditional credit card and using it anywhere, you use the app’s own environment to shop and manage payments. The appeal is straightforward: someone who has limited credit history or wants a more structured route may prefer a system that puts the purchase, payment schedule, and credit-building intention in one place.
That structure can be reassuring for a first-time user. A conventional credit card often leaves you to decide how much to spend, remember the due date, understand interest, and monitor whether a balance is becoming uncomfortable. Perpay presents a narrower workflow. You browse, choose something, review the payment arrangement, and then decide whether the commitment is sensible for your paycheck.
That last step is the one I would not skip. The app’s message about making your paycheck work harder can sound attractive, but a paycheck is not extra money simply because an app divides a purchase into payments. The purchase still has to fit your real budget. I would use Perpay only after accounting for rent, utilities, food, transport, subscriptions, and an emergency cushion.
Where it is more useful than a normal shopping app
A standard shopping marketplace is usually optimized for selection, delivery, and price comparison. Perpay adds a financial objective to the process. If your main reason for using it is to establish or improve credit behavior, the shopping catalog becomes part of a larger routine rather than the entire point of the app.
That can be valuable for a person who wants a clear, repeatable process. For example, imagine that I need a replacement household item shortly after payday. With Perpay, I would first check the full obligation, then compare the payment amount with my upcoming income, and finally decide whether the item is necessary enough to justify the commitment. The app’s value in that situation is not merely finding the item; it is forcing me to connect the purchase with a payment plan.
However, if I only want the lowest available price, the widest selection, or the fastest way to compare several retailers, a regular marketplace may be more practical. Perpay is not automatically the best shopping destination just because it includes a credit-related benefit. The financial purpose should be the reason you choose it.
The workflow I would use before making a purchase
I would begin by treating the app like a financial commitment tool, not a source of disposable spending power. Before selecting anything, I would identify the total amount involved, the timing of each payment, and what would happen to my budget if my next paycheck were smaller than expected. I would also avoid making several purchases close together simply because each individual payment looks manageable.
A useful personal rule is to separate “can I make this payment?” from “should I make this purchase?” The first question is about short-term cash flow. The second is about whether the item is necessary, whether the total cost is reasonable, and whether the commitment could interfere with existing bills. Perpay can help organize the first question, but it cannot make the second decision for you.
I would also keep the app’s payment dates visible alongside my normal banking calendar. Relying on memory is risky, particularly when several financial services are involved. A small recurring reminder can prevent the common mistake of assuming that a payment arrangement will take care of itself.
What the app’s development tells me
Perpay was released on October 19, 2018, so it is not a brand-new experiment. Its current version is 3.7.1, and the product has had time to mature beyond the earliest concept of combining shopping with credit-building. I see that history as a positive sign for people who prefer an established app over an untested financial product.
At the same time, an updated version number should not be mistaken for a guarantee that every part of the experience will feel perfect. Version updates can improve reliability, navigation, account handling, or compatibility, but they do not remove the need to read the details of a financial agreement. The practical question is whether the current app makes those details clear enough for you to make an informed choice.
For existing users, the current version is most relevant when it changes the routine they already know. After an update, I would review the payment screen, account notifications, and any confirmation pages rather than assuming that familiar buttons mean exactly the same thing. That is especially important in finance apps, where a small interface change can affect how quickly you notice an upcoming obligation.
How the current experience may help existing users
Someone already using Perpay may benefit from having shopping and credit-related activity in one ongoing routine. Instead of opening multiple apps to track a purchase and then separately think about credit progress, the user can return to the same financial context. That reduces mental switching, which is a genuine advantage when money management already feels complicated.
The strongest benefit, in my view, is behavioral rather than technical. A user who checks the app before buying, keeps commitments small, and pays consistently may develop a more deliberate relationship with installment-style spending. The app can serve as a checkpoint between wanting something and agreeing to pay for it.
There is also a useful distinction between using the app occasionally and making it part of a long-term routine. Occasional use may solve one purchase problem, while regular use requires more discipline. Existing users should periodically ask whether the service is helping them build better habits or simply making it easier to take on more commitments. If the latter is happening, reducing usage may be the healthier choice.
Important friction and remaining gaps
The biggest limitation is that convenience can hide complexity. A payment amount may look small when viewed on its own, yet several small commitments can become a significant monthly burden. This is a general risk with split-payment services, and Perpay’s credit-building angle does not eliminate it.
I would also be cautious if your income changes from week to week, if you regularly face overdraft risk, or if you are already managing several debts. In those situations, a basic budgeting tool or a nonprofit financial counselor may be more appropriate than another purchasing channel. Perpay can organize a purchase, but it is not a replacement for a complete debt plan.
Another gap is the possibility of confusing credit-building intentions with guaranteed credit results. Responsible payment behavior can be useful, but no app should be treated as a magic shortcut to a stronger financial profile. Your broader financial history, current obligations, and reporting circumstances still matter. I would use Perpay as one controlled part of a plan, never as the entire plan.
Shopping convenience can create a second kind of friction: the temptation to browse when you had no purchase in mind. I recommend opening the app with a specific need rather than exploring it casually. That simple habit changes the app from a source of impulse spending into a tool for a planned purchase.
Who should consider it, and who should skip it
Perpay may suit someone who wants a focused route into credit-related purchasing and is comfortable following a payment schedule. It can also appeal to users who prefer a guided experience over the open-ended nature of a traditional credit card. If you are organized, have predictable income, and can judge affordability using the total commitment rather than the individual payment, the app is easier to use responsibly.
I would be more hesitant to recommend it to someone who is already behind on bills, frequently depends on the next paycheck, or tends to buy more when a payment is divided into smaller pieces. In those cases, the app’s convenience could work against you. A debit-based budget, a savings-first approach, or direct debt repayment may be a better priority.
It may also be the wrong fit if your main goal is broad financial management. Perpay is not the same kind of tool as an expense tracker that categorizes every transaction, a bank account that handles daily cash, or a conventional card accepted across a wide range of merchants. Choosing it means accepting a more specific purpose.
Questions I would settle before relying on it
One question many people will have is whether the app is genuinely free to install and start using. It is listed as free, which removes an upfront download charge, but I would still read every purchase and payment detail carefully. “Free” should not be interpreted as “every transaction has no financial cost.” The important information is always the complete obligation connected to the purchase.
Another practical question is whether a person under eighteen can use it. The app carries an Everyone content rating, but that label describes content suitability rather than automatically explaining financial eligibility. Anyone considering a finance product should check the account requirements and agreement details during sign-up instead of relying on the age label alone.
People also ask whether they can use it like an ordinary credit card. I would not assume that. Perpay’s identity is built around its own shopping and payment experience, so it should be evaluated on that basis. If you need unrestricted everyday spending, travel rewards, or broad merchant acceptance, a different financial product may serve you better.
A further concern is what happens if income or circumstances change. My advice is to examine the payment terms before committing and keep enough cash available for ordinary bills. If a purchase would only work when every paycheck arrives exactly on time, it is probably too large for your current budget.
What I would watch as the product continues to evolve
For future updates, I would pay attention to clarity more than visual polish. The most valuable improvements would be easier-to-understand payment summaries, prominent reminders, and a straightforward view of current commitments. In a finance app, transparency has more practical value than decorative redesigns.
I would also watch how well the app separates shopping encouragement from responsible credit education. The strongest version of Perpay would help users understand what they are agreeing to before they browse further. If the shopping side becomes more prominent than the budgeting context, users may need to supply more of their own discipline.
Existing users should watch their update notes and revisit their account screens after installing a new version. New users should take a slower approach: install the app, explore the payment information, and wait before making a purchase. That short pause is one of the best safeguards available, regardless of how polished the current interface feels.
My final assessment
I see Perpay as a specialized finance app for people who want shopping and credit-building activity connected in one place. Its established presence, free availability, and strong user response make it worth investigating, especially if you have predictable income and a clear reason to use this particular approach.
My recommendation comes with a firm condition: use it for planned needs, keep commitments modest, and judge affordability by the complete payment obligation. Do not let a smaller installment make an unnecessary purchase appear harmless. Used carefully, Perpay can provide structure and a more deliberate purchasing routine. Used casually, it can make borrowing feel easier than it really is.
For me, that balance defines the app. It is not a universal replacement for a bank, a budget planner, or a traditional credit card. It is a focused tool that may help the right user build a more organized payment habit. If that is your goal, Perpay is worth a careful trial. If your priority is simply spending less or getting out of debt, I would start somewhere less purchase-oriented.
FAQs for Perpay - Shop and Build Credit
01What is Perpay and how does it work?
Perpay is an app designed to help users shop for products while building credit. It offers a unique platform where users can purchase items and pay over time with manageable payments. Each timely payment helps improve the user's credit score, making it an excellent tool for those looking to enhance their financial standing.
02How does Perpay affect my credit score?
Perpay reports your payment activity to major credit bureaus, which can positively impact your credit score if payments are made consistently and on time. Users should be aware that late or missed payments could have a negative effect, so it's crucial to stay on top of the payment schedule provided by Perpay.
03What are the eligibility requirements for using Perpay?
To use Perpay, you must be employed and have a steady income. The app requires users to link their bank account for verification purposes. Additionally, users should have a positive banking history as this helps determine the spending limit and approval for purchases. No credit check is required, making it accessible for many.
04Are there any fees associated with using Perpay?
Perpay does not charge interest or fees on purchases, which makes it an attractive option for those looking to avoid traditional credit card fees. However, users should be aware of any potential fees related to late payments. It’s always a good idea to review the terms and conditions within the app for detailed information.
05What products can I purchase through Perpay?
Perpay offers a wide range of products, including electronics, home goods, apparel, and more. The app partners with various retailers, providing users with access to popular brands and items. The available products can be browsed directly within the app, making it easy to find and purchase what you need.
Pros
- Simple user interface for easy navigation.
- Wide variety of products available to purchase.
- No credit check required to start.
- Automatic credit building with purchases.
- Flexible payment plans to suit budgets.
Cons
- Limited to U.S. residents only.
- Higher prices compared to traditional stores.
- Shipping can be slower than expected.
- Limited customer service response times.
- Requires consistent income for approval.

Perpay - Shop and Build Credit
Gallery